
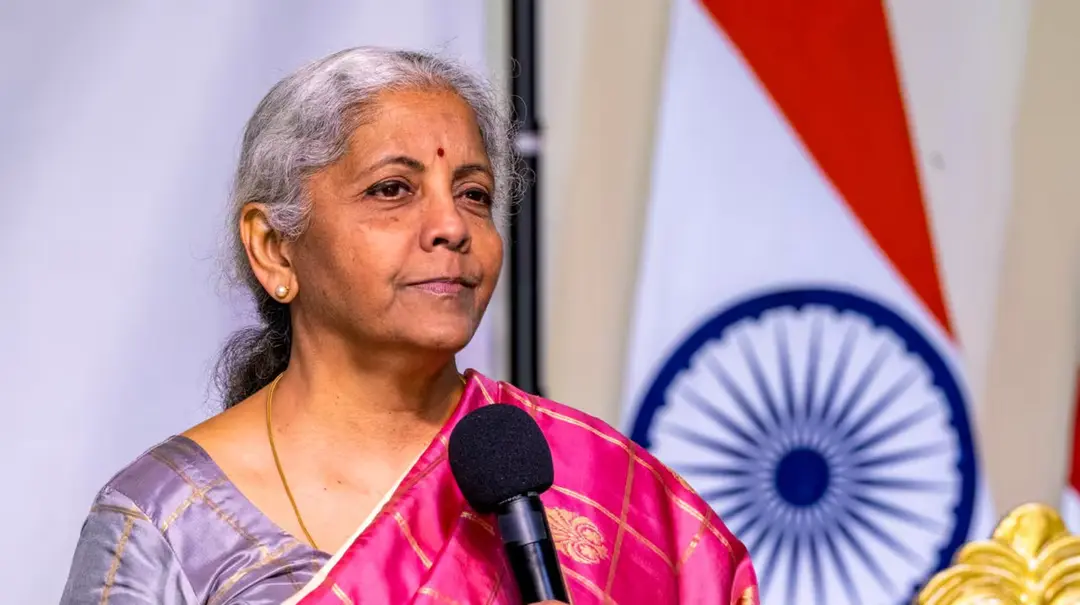
Sitharaman asks industry to name tax provisions that should go
Finance Minister Nirmala Sitharaman asked tax professionals and industry bodies to move beyond demands for lower rates and exemptions and identify tax provisions that should be removed, including those benefiting their own sectors. Speaking at ITRAF's 8th International Tax Conference in Bengaluru, she sought evidence-based proposals. She cited higher appeal thresholds — Rs 60 lakh at the ITAT, Rs 2 crore at high courts and Rs 5 crore at the Supreme Court — and said GST 2.0 process reforms were deferred to the October 7 Council meeting.
Source
Finance — Nirmala Sitharaman · read the original report ↗
Desk check · compared with the source
What the desk checked (5)
- Sitharaman asked tax professionals and industry bodies to identify tax provisions that should be removed, including those benefiting their own sectors. — Attributed to Sitharaman at ITRAF's 8th International Tax Conference in Bengaluru; direct quote provided in source.
- Appeal thresholds raised to Rs 60 lakh (ITAT), Rs 2 crore (high courts) and Rs 5 crore (Supreme Court). — Figures appear in source, cited by the minister as dispute-reduction measures; not independently verified.
- GST 2.0 has focused on rate rationalisation; process reforms deferred to the GST Council meeting on October 7. — Attributed to Sitharaman with supporting quote; date appears in source.
- There is no GST 3.0 as of now. — Stated as a clarification by the minister in the source.
- Cryptocurrency taxation remains under discussion, with transactions continuing to be taxed at source. — Attributed to Sitharaman; no supporting documentation cited in source.
Analysts’ view opinion
Asking for lower rates is easy; naming a provision your own sector profits from and asking for its removal is not — that is the challenge the Finance Minister has put to industry. Economically, this is an attempt to shift the conversation from rate politics to compliance costs, because capital locked in tax disputes, legal fees and prolonged uncertainty are all direct business expenses. Raising appeal thresholds should cut the volume of small disputes and lower transaction costs for both companies and the department, though it may mean the exchequer forgoes some contested revenue.
- The demand for evidence-based, quantified proposals — taxpayers affected, compliance costs, revenue implications — raises the cost of lobbying and could tilt influence towards larger, better-resourced industry bodies.
- Thresholds of ₹60 lakh at the ITAT, ₹2 crore at high courts and ₹5 crore at the Supreme Court can release funds tied up in small and mid-sized disputes faster.
- Fewer appeals may cost the government some revenue in the near term, with potential payback through lower administrative costs and better voluntary compliance later.
- In GST 2.0, rate rationalisation came first while process reform was deferred to October 7 — meaning price relief arrives ahead of the cash-flow relief businesses get from smoother returns and refunds.
- Unsettled tax treatment of cloud and crypto keeps uncertainty over tech-sector investment decisions, while the signalled leniency for space-sector R&D reads as an investment-friendly nudge.
What to watch — Watch how far the October 7 GST Council meeting takes process reforms on returns, refunds and registration — that is where genuine compliance-cost savings will be decided.
The story does not establish which provisions would actually be removed, what revenue they involve, or how much litigation the higher appeal thresholds have already reduced — these remain intentions, not commitments.
Deep dive
Research brief · 8 facts · 2 dates · exam-readyThe brief
Context
At the International Tax Research and Analysis Foundation's (ITRAF) 8th International Tax Conference in Bengaluru, Finance Minister Nirmala Sitharaman urged tax professionals and industry bodies to stop confining their submissions to demands for lower rates and exemptions, and instead point to provisions that should be scrapped — even ones from which their own sectors benefit. She framed the government's tax reform approach as aimed at reducing litigation at source rather than merely managing the existing backlog of disputes. She also updated the status of GST 2.0, saying rate rationalisation has been done while process reforms go to the GST Council meeting scheduled for October 7, and flagged the difficulty of taxing the digital economy, crypto, cloud computing and the space sector.
Key facts
- Sitharaman spoke at ITRAF's 8th International Tax Conference in Bengaluru, asking industry to identify tax provisions that should be removed, including ones benefiting their own sectors.
- She asked for evidence-based, quantified proposals stating number of taxpayers affected, compliance costs, revenue implications and possible unintended consequences.
- Monetary threshold for departmental appeals raised to Rs 60 lakh before the Income Tax Appellate Tribunal (ITAT).
- Threshold for departmental appeals before high courts raised to Rs 2 crore, and before the Supreme Court to Rs 5 crore.
- GST 2.0 has so far focused on rate rationalisation; process reforms were deferred to the next GST Council meeting scheduled for October 7.
- Sitharaman clarified there is no GST 3.0 as of now, as the government is still working on GST 2.0.
- On cryptocurrency, the government has chosen to wait for greater stakeholder clarity while continuing to tax transactions at source.
- On the space sector, she said commercial operations are 'fair play for tax' while R&D activities could get a more lenient approach.
Timeline
- Wednesday (report dated September 16)Sitharaman addresses ITRAF's 8th International Tax Conference in Bengaluru, asks industry to name provisions for removal and outlines litigation-reduction measures.
- October 7 (first week of October)Next GST Council meeting scheduled, where the deferred GST process reform agenda is to be discussed.
Who has a stake
- Finance Minister Nirmala Sitharaman / Ministry of Finance — Driving a tax reform agenda focused on reducing litigation, easing voluntary compliance and limiting enforcement to genuine cases.
- Tax professionals and industry bodies — Asked to shift from sector-specific demands for rate cuts and exemptions to evidence-based proposals, including surrendering provisions that benefit them.
- GST Council — Will take up the deferred process reform agenda of GST 2.0 at its October 7 meeting after rate rationalisation.
- ITAT, high courts and the Supreme Court — Higher monetary appeal thresholds (Rs 60 lakh / Rs 2 crore / Rs 5 crore) are meant to cut the volume of departmental tax appeals before them.
- Digital economy players — crypto, cloud computing firms — Face unresolved questions on taxation; crypto transactions continue to be taxed at source pending greater clarity.
- Space sector companies — Commercial operations liable to tax, while R&D activities may get leniency.
- ITRAF (International Tax Research and Analysis Foundation) — Host of the conference; urged, along with other institutions, to contribute to policymaking via independent research.
Why it matters
Tax litigation and compliance complexity are long-standing drags on India's business environment, and the Minister's ask signals a shift from bargaining over rates to pruning the statute book itself. Higher appeal thresholds and the promised GST process reforms would directly affect how many disputes reach tribunals and courts. The unanswered questions on crypto, cloud and space taxation show where India's next tax design battles lie.
UPSC angle
Prelims pointers
- Departmental appeal thresholds cited: Rs 60 lakh (ITAT), Rs 2 crore (high courts), Rs 5 crore (Supreme Court).
- ITRAF = International Tax Research and Analysis Foundation; its 8th International Tax Conference was held in Bengaluru.
- GST 2.0 so far = rate rationalisation; process reforms deferred to the GST Council meeting on October 7.
- Sitharaman said there is no GST 3.0 as of now.
- Crypto: government continues to tax transactions at source while awaiting greater stakeholder clarity.
- Space sector: commercial operations taxable; R&D to be treated leniently, per the Finance Minister.
Mains framing
India's tax reform debate has traditionally been driven by demands for lower rates and sectoral exemptions, which multiply provisions, raise compliance costs and feed litigation. Sitharaman's call for stakeholders to nominate provisions for deletion — quantified by taxpayers affected, compliance costs, revenue implications and unintended consequences — reframes reform as simplification of the statute rather than concession-seeking, and complements measures such as higher monetary thresholds for departmental appeals (Rs 60 lakh at ITAT, Rs 2 crore at high courts, Rs 5 crore at the Supreme Court) that aim to prevent disputes rather than merely clear the backlog. On the indirect tax side, GST 2.0 has prioritised rate rationalisation, leaving process reform to the October 7 Council meeting, which is where compliance burden is most acutely felt. The harder frontier is the digital economy: determining the source of a digital product, identifying who owns cloud infrastructure, and settling crypto treatment beyond taxation at source. A credible way forward involves evidence-based pruning of redundant provisions, completing GST process reforms, a settled framework for digital and crypto taxation, and a calibrated approach in emerging sectors like space that taxes commercial activity while encouraging R&D.
Key terms
- ITRAF
- International Tax Research and Analysis Foundation, which hosted the 8th International Tax Conference in Bengaluru where the Minister spoke.
- ITAT
- Income Tax Appellate Tribunal; appellate forum where the departmental appeal threshold has been raised to Rs 60 lakh.
- GST 2.0
- The current phase of GST reform, so far centred on rate rationalisation, with process reforms pending before the GST Council.
- GST Council
- Federal body deciding GST matters; its next meeting is scheduled for October 7 to take up process reforms.
- Monetary threshold for departmental appeals
- Minimum disputed amount below which the tax department will not file appeals, used to cut litigation volume.
- Taxation at source (crypto)
- Approach of taxing cryptocurrency transactions at the point of transaction while broader policy clarity is awaited.
Practice questions
- Higher monetary thresholds for departmental appeals are described as a litigation-reduction measure. Critically examine whether such thresholds address the causes of tax disputes in India.
- "Simplification, not concession, is the next frontier of Indian tax reform." Discuss in the light of the Finance Minister's call to identify tax provisions for removal.
- Discuss the conceptual challenges in taxing the digital economy — including cloud computing and cryptocurrency — and suggest principles for an Indian framework.
Grounded only in the source report — figures and dates are the source's, not inferred.